
From hedgeable instability to the portfolio of assumptions
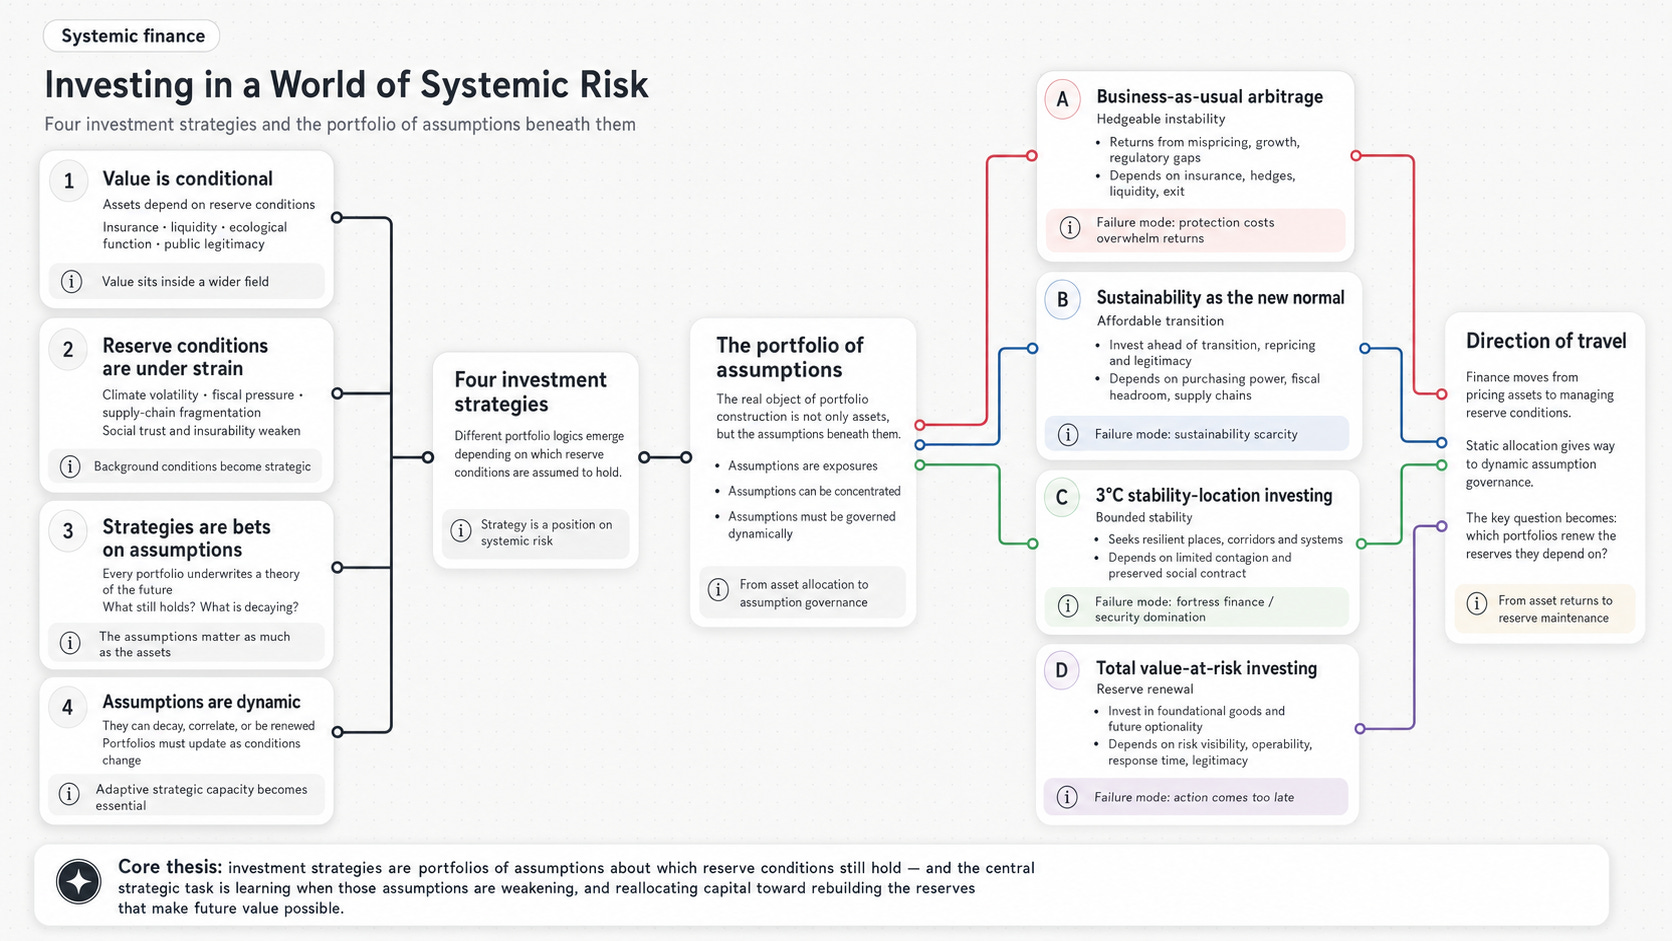
There is a quiet assumption sitting beneath much of modern finance. It is the assumption that value can still be understood primarily at the level of the asset, the company, the project, the fund or the portfolio. This assumption is not obviously wrong. It is how most financial analysis has been organised for decades. Assets have cash flows, companies have balance sheets, funds have strategies, and portfolios have risk-adjusted returns. The analytical unit is bounded, modelled and priced.
But this assumption is becoming increasingly insufficient. Not because asset-level analysis is irrelevant, but because the conditions that make assets valuable are becoming unstable.
A building is not valuable in isolation. It is valuable because the city around it remains insurable, governable, serviced, inhabited and economically active. A logistics business is not valuable in isolation. It is valuable because ports, roads, fuel systems, trade routes, legal systems, labour systems and geopolitical arrangements continue to function. A food business depends on soil, water, climate, fertiliser, labour, energy, distribution networks and consumer purchasing power. A technology company depends on energy, data governance, legitimacy, skilled labour, social trust and state tolerance.
Financial value is therefore always conditional value. It is produced not only by the asset itself, but by a wider field of conditions that make the asset operable, defensible and valuable.
I want to call these reserve conditions.
By reserve conditions, I mean the underlying capacities that allow financial value to remain viable over time. Some are financial reserves: liquidity, insurance, hedges, credit availability and exit pathways. Some are institutional reserves: legal continuity, regulatory competence, public legitimacy, enforceable contracts and capable states. Some are ecological reserves: water, soil, biodiversity, climate stability and functioning ecosystems. Some are social reserves: trust, cohesion, consumer purchasing power, health, skills and the social contract. Some are geopolitical reserves: secure trade routes, supply-chain coherence, peaceful borders, energy security and non-fragmented markets. Some are temporal reserves: the time between risk becoming visible and risk becoming irreversible.
For a long time, finance could afford to treat many of these reserves as background conditions. They appeared as context rather than as value. They were assumed to be there. That assumption is now under pressure.
Climate volatility is weakening insurability. Ecological degradation is undermining food, water, health and settlement systems. Geopolitical conflict is fragmenting supply chains. War economies are absorbing public resources. Inflation is eroding household purchasing power. Public balance sheets are being stretched by climate disasters, ageing populations, debt servicing, defence spending and emergency response. Biodiversity loss is raising the true cost of ecological repair. Social trust is weakening. Infrastructure is ageing. Political systems are struggling to coordinate long-duration transitions.
This changes the central investment question. It is no longer enough to ask which asset will outperform. We also have to ask what reserve conditions a given investment strategy depends on, and whether those reserves are being preserved, exhausted, hedged, privatised or rebuilt.
Seen in this way, the coming investment landscape can be read through four broad strategies. These are not simply four sectors or four asset classes. They are four different theories of the future. Each makes a different bet about systemic risk. Each depends on a different set of reserves. Each has a different failure mode.
The first is business-as-usual arbitrage: the strategy of hedgeable instability. The second is sustainability as the new normal: the strategy of affordable transition. The third is 3°C stability-location investing: the strategy of bounded stability. The fourth is total value-at-risk investing: the strategy of foundational reserve renewal.
These should not be read as clean chronological stages. They are simultaneous portfolio logics. A large allocator may hold all four at once. The point is not that one is simply right and the others are simply wrong. Each may make sense within particular mandates, time horizons and risk appetites. The deeper question is whether the assumptions beneath each strategy still hold, and how quickly those assumptions are changing.
That is the hidden issue running through the whole argument. Investment strategies are not only allocations of capital. They are allocations of belief. They are portfolios of assumptions.
1. Business-as-usual arbitrage: the strategy of hedgeable instability
The first strategy is the familiar one. It is the default strategy of much of the existing financial system: continue to arbitrage the world as it is.
This strategy assumes that the current operating model broadly continues. Markets remain functional. Assets remain tradable. Insurance remains available. Liquidity remains accessible. Public systems absorb shocks. Supply chains remain repairable. Jurisdictions remain open to capital mobility. Growth, even if uneven and volatile, remains the background expectation.
The investment logic is recognisable. Identify inefficiencies, exploit mispricing, optimise capital structures, arbitrage regulatory differences, capture growth, rotate exposure, and generate returns from the continuation of the existing system.
There is nothing naïve about this in the short term. Business-as-usual can still produce significant returns. The existing system has enormous inertia, and those who understand its contradictions may still be able to extract value from them. But the phrase “business as usual” is misleading if it suggests simple confidence in continuity. In practice, this strategy increasingly depends on an expanding defensive architecture around the portfolio.
It depends on insurance, hedges, liquidity buffers, exit rights, jurisdictional optionality, contractual protections, political permissions, regulatory flexibility and the capacity to move out of exposed positions before risks crystallise.
Business-as-usual is therefore not really a strategy of stability. It is a strategy of protectable instability.
It works while instability can be privately managed. It works while risk can be priced, insured, hedged, transferred or exited. It works while the investor can extract value from an exposed system without having to repair the deeper conditions on which that system depends.
The problem is that the cost of this protection is rising. Insurance becomes more expensive or unavailable. Hedging becomes more complex. Liquidity becomes more precious. Exit becomes more crowded. The political legitimacy of abandoning exposed assets, workers, places or communities becomes more contested. The ability to move capital away from risk becomes dependent on market depth, regulatory permission, buyer confidence and political tolerance.
This creates a fundamental contradiction. Business-as-usual depends on reserves it does not necessarily replenish. It relies on public institutions, ecological systems, insurance markets, liquidity pools, geopolitical order and social legitimacy to absorb the consequences of the system from which it extracts value.
This does not mean business-as-usual disappears. It may become more concentrated, more political and more dependent on privileged access to protection. It may continue to work for actors close enough to liquidity, sovereign support, jurisdictional arbitrage, political influence and superior information. But that only reinforces the point. The returns increasingly come from access to reserves rather than from productive value creation alone.
The question, then, is not whether business-as-usual can continue to generate returns. It can. The more important question is whether those returns exceed the rising cost of hedging, insuring, defending and exiting the consequences of systemic instability.
Once the cost of protection exceeds the surplus generated by extraction, business-as-usual stops being rational even on its own terms.
2. Sustainability: the strategy of affordable transition
The second strategy assumes that sustainability becomes the next baseline of investability.
This is the view that regulation, consumer demand, procurement rules, carbon pricing, litigation risk, institutional mandates, reputational pressure, insurance costs and technological innovation will progressively force the economy toward lower-carbon, lower-impact and more responsible operating models.
Under this thesis, sustainability is not concessionary. It is not philanthropy. It is the next normal of competitive advantage. The investment logic is to move ahead of the curve: into clean energy, circular materials, low-carbon buildings, nature-positive infrastructure, electrification, efficiency, transition technologies, sustainable food systems, green industrial production and companies positioned to benefit from the repricing of externalities.
This is the classic sustainability-alpha thesis. The winners are those who correctly anticipate the direction of regulation, legitimacy and market transition before it becomes mandatory.
But the sustainability thesis contains a set of assumptions that are now becoming more fragile.
It assumes, first, that consumers still have the financial capacity to participate in the transition. They must be able to pay for cleaner products, home retrofits, electric vehicles, heat pumps, low-carbon food, sustainable housing, better materials and transition-aligned services. Much of the sustainability thesis still relies, directly or indirectly, on consumer adoption. But if real incomes are squeezed by inflation, housing costs, energy volatility, debt burdens and insecurity, the ability of households to allocate purchasing power toward sustainable consumption weakens.
It assumes, second, that governments still have the fiscal headroom to invest in transition infrastructure. The sustainability thesis depends on public investment in grids, transport, housing, industrial policy, nature restoration, skills, adaptation, research, procurement and social protection. But if state balance sheets are increasingly pressured by war economies, defence spending, climate disasters, healthcare costs, demographic ageing, debt servicing and emergency response, the fiscal capacity to fund an orderly transition becomes constrained.
It assumes, third, that climate breakdown does not disrupt the transition faster than transition infrastructure can be built. Rising volatility, climate whiplash, crop failures, flooding, fires, heatwaves, droughts and insurance withdrawal can all generate inflationary pressure and fiscal stress. Climate impacts do not merely strengthen the moral case for sustainability. They can impair the economic and political capacity to deliver it.
It assumes, fourth, that geopolitics does not fragment global supply chains faster than the transition can reorganise them. The sustainability economy depends on critical minerals, clean technology supply chains, manufacturing capacity, shipping routes, trade stability, standards coordination and global capital flows. If geopolitical conflict, sanctions, trade wars, resource nationalism and security competition disrupt these systems, the cost and pace of transition become much harder.
It assumes, fifth, that biodiversity loss and ecological degradation have not advanced so far that the cost of repair becomes politically and economically unbearable. If soil systems, water systems, pollination, fisheries, forests and wider ecological interdependencies are significantly impaired, then the cost of genuinely pricing nature into the economy may become very high. Under conditions of inequality, that cost cannot simply be passed through to consumers without creating backlash, affordability crises or legitimacy failure.
The deeper point is that whether the transition is consumer-led, procurement-led, regulation-led or infrastructure-led, affordability must be absorbed somewhere in the system. The costs fall on households, firms, states, lenders, insurers, future taxpayers or future balance sheets. Under systemic stress, that absorption capacity becomes the binding constraint.
This is the vulnerability of the sustainability strategy. It assumes there is still enough surplus in the system to pay for transition without breaking the social contract.
Its hidden dependency is therefore not just transition orderliness. It is transition affordability under conditions of systemic stress.
Sustainability depends on consumer purchasing power, public investment, fiscal headroom, geopolitical coordination, ecological headroom, credible standards, functioning supply chains, institutional trust and political legitimacy. If those reserves erode, sustainability does not become a smooth new normal. It becomes contested, rationed, inflationary and politically unstable.
This does not make the sustainability strategy wrong. It makes it incomplete. A serious sustainability strategy can no longer rely only on green consumer demand, ESG repricing, regulatory tightening or corporate transition plans. It must invest in the underlying conditions that make transition affordable, legitimate and materially possible.
That means investing in lower-cost transition pathways, shared infrastructure, grid readiness, circular supply chains, household affordability, industrial capacity, ecological repair, fiscal innovation, transition skills, institutional trust and public legitimacy.
The strategic question is no longer simply which companies are best positioned for the sustainable transition. It is what must be built so that the sustainable transition remains socially affordable, fiscally possible, materially secure and politically legitimate.
Without that, sustainability alpha collapses into sustainability scarcity.
3. Investing in a 3°C world: the strategy of bounded stability
The third strategy starts from a harder assumption. It uses a 3°C world not as a forecast with false precision, but as a stress scenario. It asks what investment logic looks like when climate disruption is no longer marginal, episodic or locally containable, but structurally reshapes the geography of value.
In this stress scenario, we are no longer investing only to prevent climate breakdown, nor simply in a world of manageable adaptation. We are considering a world of deeper heat stress, crop instability, water disruption, insurance withdrawal, infrastructure fragility, migration pressure, public health crises, fiscal stress, social contract breakdown and geopolitical volatility.
This strategy asks where value remains viable under conditions of systemic climate disruption.
The investment logic moves from sustainability to spatial resilience. It seeks locations, infrastructures, jurisdictions, supply chains and institutions that can retain stability in a destabilising world. These may include cooler geographies, water-secure regions, politically stable jurisdictions, resilient food systems, strong public institutions, adaptive cities, protected infrastructure corridors, energy-secure regions and places with high social trust.
There is a real logic here. The geography of value will change. Some places will become more exposed. Some places may become relatively more viable. Some infrastructures will become more strategically important. Some jurisdictions may retain trust, capability and continuity better than others. Some places may become stability locations: places where institutional, ecological and economic functionality persists despite wider breakdown.
But this strategy depends on a very strong assumption: that stability can still be separated from breakdown.
It assumes that some locations can remain investable because they are sufficiently insulated from climate volatility, social disorder, geopolitical conflict, migration pressure, supply-chain collapse, insurance failure and institutional breakdown elsewhere. It assumes that there are places where the contagion effects of a high-disruption world can be contained or managed.
This is not guaranteed.
In a deeply disrupted world, instability does not remain neatly local. Breakdown travels through food prices, energy systems, migration flows, insurance markets, public balance sheets, security politics, supply chains, capital markets, disease ecologies, information systems and geopolitical alliances. A drought in one region can become food inflation in another. A failed insurance market can become a municipal fiscal crisis. Migration pressure can become border militarisation. Climate shocks can intensify conflict, and conflict can redirect capital away from transition and resilience into defence, surveillance and coercive security.
The 3°C strategy therefore rests on the idea that some places can become stability locations. But there is a further assumption: that these stability locations will be valued through financial economics rather than subordinated to security economics.
In a high-breakdown world, value may no longer be allocated primarily through normal market mechanisms. Strategic land, water, food, energy, minerals, ports, data infrastructure, compute capacity, logistics corridors and resilient cities may become objects of national security, geopolitical competition, military strategy, sovereign control or emergency governance. If that happens, the financial value of resilient locations may be subordinated to security value.
The market may not simply price stability. States may seek to control it.
This creates a fundamental tension. The investment thesis assumes that resilient places become financially valuable. But in a high-disruption world, the most resilient places may become politically sensitive, securitised or contested. Their value may be real, but not freely investable, tradable or extractable.
The strategy also depends on the preservation of the social contract. A resilient location is not resilient merely because it has water, cooler temperatures, energy systems or strong infrastructure. It must also retain legitimacy. It must preserve a working social contract internally, and it must withstand the cascade effects of social contract breakdown externally.
If neighbouring regions experience food insecurity, displacement, political collapse or conflict, the stability location cannot assume insulation. It may face migration pressure, security escalation, trade disruption, moral-political obligations, fiscal burdens and legitimacy challenges. The question becomes not only whether a place is physically resilient, but whether it can maintain social coherence under surrounding instability.
So a 3°C investment strategy cannot simply be a map of “safe places”. It must be an assessment of contagion risk. Can a location preserve public order without becoming authoritarian? Can it absorb migration pressure without social breakdown? Can it maintain food, water, energy and health systems under external shocks? Can it preserve legitimacy while defending scarce resources? Can it remain open enough to function economically while secure enough to withstand volatility? Can it avoid being pulled into the war economy? Can it preserve financial value if the wider operating environment shifts from market economics to security economics?
The hidden dependency of the 3°C strategy is bounded stability under contagion pressure.
Its vulnerability is that climate breakdown may become socially, geopolitically and economically contagious faster than resilient locations can insulate themselves. If systemic conflict, territorial competition, forced migration, supply-chain militarisation, fiscal collapse or total war dynamics emerge, then much of the normal financial logic behind resilient-location investing becomes non-viable.
This is why the strategy is both powerful and dangerous. It is powerful because it recognises that the geography of value will change. It is dangerous because it can slide into fortress investing: capital seeking refuge from systemic breakdown rather than investing to reduce breakdown itself.
Fortress investing may create private safety for some, but it does not solve systemic risk. It can intensify inequality, securitise territory, abandon exposed populations and accelerate the politics of exclusion.
A serious 3°C strategy therefore has to move beyond defensive resilience. It must invest not only in protected locations, but in the relational stability between places. Stability is not only a property of isolated locations. It is a relational condition produced across food systems, migration systems, energy systems, security systems, neighbouring regions and political settlements.
The aim cannot only be to identify the places that survive. It must be to invest in the conditions that prevent the geography of survival from becoming a geography of conflict.
4. Total value-at-risk investing: the strategy of reserve renewal
The fourth strategy is the deepest and most systemic.
It begins from the assumption that we are not only facing climate risk, transition risk or adaptation risk. We are facing total value at risk.
Traditional value-at-risk asks what a portfolio may lose under adverse market conditions. Total value-at-risk asks what markets, assets and institutions may lose when the conditions of market functioning themselves degrade.
Total value at risk is the full field of financial, ecological, institutional, social and political value exposed when the conditions that make assets valuable begin to fail.
In this thesis, the greatest risk is not asset impairment. It is context impairment.
A building loses value if the city around it becomes uninsurable. A logistics business loses value if supply chains become structurally unreliable. A food company loses value if soil, water, fertiliser, energy and climate systems destabilise. A technology company loses value if energy, legitimacy, data governance and public trust collapse. A financial portfolio loses value if the public, ecological and institutional systems beneath it can no longer absorb volatility.
This strategy therefore asks a more fundamental investment question: what foundational goods must be rebuilt, protected or transformed so that future value remains possible?
The answer includes water, food, energy, shelter, care, cooling, health, ecological integrity, civic trust, institutional capacity, public intelligence, democratic correction, local resilience and the capacity of places to organise around shared futures.
These are often misclassified as public goods, social costs or externalities. But in a world of systemic risk, they become the substrate of all future value. The investment logic is not simply to invest in assets. It is to invest in the reserve conditions under which assets remain meaningful, governable, insurable and valuable.
But this fourth strategy should not be romanticised. It also contains assumptions. It does not escape the constraints of time, visibility, action and legitimacy.
The first assumption is that there is a gap between risk being real and risk becoming visible. Systemic risk often accumulates before it is legible. Soil degradation, water stress, institutional decay, insurance withdrawal, public distrust, supply-chain fragility, biodiversity collapse and fiscal weakness can all build beneath the surface before they appear as market signals. By the time risk becomes visible, the underlying system may already be significantly impaired.
The second assumption is that there is a gap between risk becoming visible and risk becoming actionable. Visibility does not automatically produce action. Markets may see the risk and still fail to move. Governments may understand the risk but lack fiscal space, legitimacy or coordination capacity. Institutions may model the risk but not know how to convert it into mandates, budgets, projects, contracts or investable structures. Citizens may experience the risk but lack the power to force correction. Capital may recognise the risk but lack the instruments to invest in the underlying solution.
This is a critical gap. Risk can be visible and still remain non-operable.
The third assumption is that there is a gap between crisis manifestation and response capacity. Crises do not manifest everywhere at once. They appear in particular places, sectors, infrastructures and populations before cascading outward. Total value-at-risk investing assumes that actors can learn from crisis manifestation in one place and operationalise protective or transformative strategies elsewhere before the risk propagates. It assumes there is enough time between signal and cascade, between local breakdown and systemic contagion, between visible failure and wider collapse.
This may not always hold. Some crises move faster than institutions can learn. Some failures cascade before capital can be mobilised. Some risks become politically contested before they become investable. Some disasters consume the fiscal, administrative and civic capacity needed to respond. In those contexts, visibility comes too late, actionability is too slow, and optionality closes before it can be preserved.
The fourth assumption is legitimacy. Even when risk is visible and technically actionable, the proposed response may not be socially authorised. In systemic contexts, legitimacy is not an accessory to execution. It is part of the operating infrastructure of action. Adaptation, relocation, ecological repair, water reallocation, new infrastructure, land-use change, food-system transformation and security-linked investment all require legitimacy if they are to endure. Without it, action becomes contested, delayed, litigated, resisted or coercive.
This means total value-at-risk investing depends on four temporal and institutional reserves. It depends on risk visibility: the ability to perceive systemic risk before collapse. It depends on risk operability: the ability to convert visible risk into mandates, vehicles, contracts and investments. It depends on response time: the interval between crisis manifestation and irreversible option closure. And it depends on legitimacy: the social and institutional authorisation required to act at scale without destroying trust.
The hidden dependency of total value-at-risk investing is therefore legitimate, actionable foresight under closing time horizons.
Its vulnerability is that systemic risk may become visible too late, actionable too slowly, legitimate too weakly, or cascade too quickly for capital and institutions to preserve optionality.
This makes the fourth strategy urgent. It cannot wait for perfect evidence, perfect pricing or perfect consensus. If it waits until the risk is fully visible, it may already be too late. If it waits until the value is fully priced, the option may already be closed. If it waits until crisis has manifested everywhere, the reserves required for response may already be exhausted.
Total value-at-risk investing therefore requires anticipatory institutions. It requires risk-sensing infrastructures, civic intelligence, early-warning systems, place-based observatories, adaptive mandates, pre-authorised capital, rapid contracting capacity, pooled governance and vehicles capable of acting before risk becomes fully priced.
Its strategic function is to close the gap between risk visibility and legitimate action.
This is why total value-at-risk investing is not simply another sustainability strategy. It is a different theory of finance. It does not begin with the asset. It begins with the field of conditions that make assets possible. It does not ask only what can generate return. It asks what must remain viable for return to exist. It does not treat public goods as externalities. It treats them as the operating substrate of future value. It does not rely on exit. It recognises that in a world of systemic risk, the real frontier is repair.
The assumptions beneath the portfolio
There is a deeper point beneath these four strategies. The strategies are not merely different ways of allocating capital. They are different ways of underwriting assumptions about the world. Each carries a view about what will remain stable, what will become scarce, what can still be hedged, what can still be governed, what can still be afforded, what can still be exited, and what can still be repaired.
That means the real object of portfolio construction is not only the portfolio of assets. It is also the portfolio of assumptions that sits beneath those assets.
This is a subtle but important shift. In conventional investment practice, assumptions are often treated as inputs to strategy: growth assumptions, inflation assumptions, policy assumptions, demand assumptions, discount-rate assumptions, climate assumptions, regulatory assumptions and geopolitical assumptions. They sit inside the model. They are tested, stressed and adjusted, but they are not usually treated as a live portfolio in their own right.
In a world of systemic risk, that is no longer enough. Assumptions themselves become strategic exposures. They can become crowded. They can become correlated. They can decay. They can be hedged. They can be diversified. They can become obsolete faster than the assets they were designed to price. Critically, they can also change because of the actions of the investors who hold them.
This is perhaps the most important implication of the four-strategy framework. The future of investment is not only about choosing strategies. It is about dynamically governing the assumptions that make those strategies valid.
An investor holding business-as-usual assets is not only exposed to the assets themselves. They are exposed to the assumption that insurance markets will remain functional, liquidity will remain available, exit will remain possible and political systems will continue to permit private escape from systemic risk. An investor holding sustainability assets is not only exposed to clean technology or regulation. They are exposed to the assumption that households, governments and firms can still absorb the cost of transition. An investor holding resilient-location assets is not only exposed to geography. They are exposed to the assumption that instability elsewhere will not become contagious enough to overwhelm the value of place-based resilience. An investor pursuing total value-at-risk strategies is exposed to the assumption that systemic risk can become visible, actionable and legitimate before optionality closes.
Every portfolio therefore has two layers. There is the visible portfolio of assets, and there is the less visible portfolio of assumptions. The visible portfolio may look diversified while the assumption portfolio is highly concentrated. A fund may hold real estate, infrastructure, technology, consumer goods and energy assets, yet all of them may depend on the same hidden assumption: that social order, insurance, fiscal capacity and supply chains remain intact. That is not true diversification. It is asset diversification sitting on top of assumption concentration.
The more systemic risk grows, the more dangerous that becomes.
Traditional diversification spreads exposure across assets, sectors, geographies and currencies. But systemic risk can move through all of these at once. It can correlate what previously looked uncorrelated. Climate shocks can become food inflation, which becomes political volatility, which becomes fiscal stress, which becomes insurance withdrawal, which becomes real estate repricing, which becomes municipal credit risk. In that world, asset categories do not tell the whole story.
The more important question becomes: what assumptions are being diversified?
A portfolio may need some exposure to the business-as-usual thesis because existing systems have inertia and can continue to generate returns. It may need exposure to sustainability because regulation, technology and legitimacy may still drive transition. It may need exposure to resilience and adaptation because climate disruption is already changing the geography of value. It may need exposure to total value-at-risk strategies because the deepest opportunity may lie in rebuilding the conditions that make all other value possible.
But the weighting between these strategies cannot be fixed. It has to evolve as the underlying assumptions become more or less credible. The task is not to declare one scenario right and allocate accordingly. The task is to hold a portfolio of assumptions, monitor their decay, and shift capital as the evidence changes.
That is a very different kind of investment discipline. It is less about prediction and more about adaptive positioning.
The question becomes: what would have to be true for each strategy to work, and what evidence would tell us that those conditions are weakening?
Assumption drift as investment risk
A major risk in this environment is assumption drift. This happens when the world changes faster than the investment thesis is updated.
The asset may still look attractive on its own terms. The model may still show return. The market price may still appear rational. But the assumptions beneath the asset may already be deteriorating.
A real estate asset may still be cash-flow positive while the insurance assumption beneath it is weakening. A consumer sustainability company may still show demand growth while household purchasing power is beginning to erode. A resilient region may still look investable while nearby social or geopolitical contagion risks are rising. A total value-at-risk strategy may correctly identify systemic risk while the window for legitimate action is closing.
The danger is that investors often update assets faster than they update assumptions. They reprice visible shocks, but they underreact to the slow deterioration of background conditions.
This is why the governance of assumptions becomes critical. A serious capital allocator would need to know not only what it owns, but what assumptions it is relying on; not only how those assumptions are performing, but how quickly they are changing; not only whether the current strategy is working, but what would cause the strategy to be retired, reduced, hedged or replaced.
In this sense, assumption management becomes a form of risk management. But it is also more than risk management. It becomes a source of strategic advantage.
Dynamic strategy requires more than a dashboard of indicators. It requires the capacity to change investment behaviour when assumptions change. That is institutionally difficult. Mandates are often fixed. Committees are slow. Incentives reward consistency. Benchmarks punish deviation. Political and reputational risks discourage early movement. Legal structures can trap capital in yesterday’s assumptions. Even when risk becomes visible, it may not become actionable.
So the ability to evolve investment strategy dynamically becomes a reserve condition in its own right.
Beneath the financial reserves of business-as-usual, the transition reserves of sustainability, the spatial stability reserves of the 3°C strategy and the temporal reserves of total value-at-risk lies another reserve: adaptive strategic capacity. This is the capacity to notice when assumptions are changing, to interpret what the change means, to alter mandates, to move capital, to build new vehicles, to preserve legitimacy and to act before the window closes.
Without that capacity, even a sophisticated portfolio can become trapped. It may understand the future conceptually but remain operationally tied to the past.
Reflexive assumptions
There is another complication. Assumptions are not purely external. Investment strategies can help make their own assumptions more or less true.
If enough capital pursues business-as-usual extraction while relying on exit, it can weaken the very reserves that make exit possible. It can drain public systems, increase inequality, intensify ecological stress and reduce legitimacy. In doing so, it makes the assumption of hedgeable instability less credible.
If enough capital invests in transition affordability, grid capacity, industrial renewal, household resilience and ecological repair, it can make the sustainability assumption more credible. It can help keep transition socially and politically viable.
If enough capital pursues fortress resilience, buying into protected locations while abandoning exposed regions, it can increase contagion risk. It can make the 3°C stability-location thesis less stable by accelerating inequality, migration pressure and geopolitical insecurity.
If enough capital invests in risk visibility, early-warning systems, civic intelligence, institutional capacity and foundational goods, it can improve the conditions for total value-at-risk investing. It can make systemic risk more visible, more actionable and more legitimate to address.
Investment strategies are therefore not just responses to future conditions. They participate in producing future conditions.
That is crucial. The assumption portfolio is not passive. It is reflexive. Capital does not merely bet on whether reserves will hold. It can consume, defend, privatise or regenerate those reserves.
This is why the earlier distinction matters so much: which portfolios renew the reserves they depend on, and which portfolios consume them?
From assumption agility to investment architecture
There is therefore a meta-strategy above the four strategies. It is not a fifth strategy in the same sense. It is the capacity to hold, test and evolve all four.
This meta-strategy asks: what is our current portfolio of assumptions? Which assumptions are we most exposed to? Which assumptions are becoming more fragile? Which assumptions are correlated with one another? Which assumptions would fail together? What would we need to see to change our view? How quickly could we act if our view changed? What mandates, vehicles, permissions and governance structures would allow us to move before the market fully reprices the risk?
In a more conventional world, investors could afford to optimise around a relatively stable set of assumptions. In a systemic-risk world, the assumptions themselves are unstable. So the edge shifts from static optimisation to dynamic interpretation.
This does not mean constant trading or tactical churn. In fact, it may mean the opposite. The most important investments may be long-duration commitments to resilience, institutional capacity, ecological repair and transition affordability. But those commitments need to be made within an adaptive framework that can recognise when the context has changed.
The key is not simply speed. Fast capital can be destructive if it becomes exit-driven, extractive or pro-cyclical. The key is legitimate adaptability: the ability to change strategy without amplifying the breakdown one is trying to manage.
That distinction matters. Dynamic capital that simply exits early can worsen systemic risk. Dynamic capital that reallocates towards repair can preserve optionality. Both are adaptive, but only one renews the field of value.
If assumptions are exposures, they need governance. That does not mean turning every assumption into a rigid model. Many of the most important assumptions will be qualitative, contested and uncertain. But they still need to be named, monitored and debated.
An investment committee should not only ask whether a deal meets its return threshold. It should ask which theory of the future the deal depends on, which reserve conditions it consumes, which it strengthens, and what would invalidate the thesis.
For business-as-usual investments, the committee would ask whether the asset’s risks remain insurable, hedgeable, liquid and politically exitable. For sustainability investments, it would ask whether the transition remains affordable for households, deliverable by states, secure in supply chains and legitimate in distribution. For 3°C stability-location investments, it would ask whether the location’s stability is genuinely resilient or merely temporarily insulated from external contagion. For total value-at-risk investments, it would ask whether the risk is visible early enough, actionable through existing or new vehicles, legitimate to address, and still within a window where optionality can be preserved.
This kind of governance would create an assumption register, but not as a bureaucratic exercise. It would function as a live map of strategic exposure. The purpose would not be to eliminate uncertainty. That is impossible. The purpose would be to know which uncertainties the portfolio is underwriting.
The best investors in this world may not be those who claim to forecast the future most accurately. They may be those who know most clearly what they are assuming, how those assumptions are changing, and what they will do when those assumptions fail.
Assumption decay and strategic movement
One practical implication is that portfolios need triggers for assumption decay.
An assumption does not usually fail all at once. It weakens. Insurance becomes more expensive before it disappears. Household purchasing power erodes before demand collapses. Fiscal headroom narrows before public investment stops. Supply chains become more politicised before they fragment. Social trust declines before the social contract breaks. Climate volatility increases before a place becomes uninsurable. Risk becomes visible before it becomes fully priced.
The value lies in recognising the weakening of assumptions before the market treats them as obvious.
That suggests a different kind of portfolio intelligence. Instead of monitoring only asset prices, earnings, rates and policy announcements, investors would monitor the reserve conditions beneath their strategies. They would watch the cost and availability of insurance, the political tolerance for exit, the affordability of transition, the fiscal capacity of states, the resilience of supply chains, the legitimacy of institutions, the spread of conflict dynamics, the movement of migration pressure, the health of ecosystems, and the speed with which visible risks become actionable.
The question is not simply whether these indicators are “bad”. It is whether they are moving in a way that invalidates the assumptions beneath a strategy.
When the assumption of hedgeable instability weakens, the portfolio should move away from pure business-as-usual extraction. When the assumption of affordable transition weakens, the portfolio should move from sustainability winners towards transition affordability and shared infrastructure. When the assumption of bounded stability weakens, the portfolio should move from safe-haven selection towards contagion reduction and regional stability. When the assumption of actionable foresight weakens, the portfolio should invest in the institutions that make risk visible, operable and legitimate earlier.
In other words, assumption decay should not only trigger defensive movement. It should trigger a shift towards the investment strategy that rebuilds the failing reserve.
Optionality reconsidered
This changes how we understand optionality.
In finance, optionality often means the ability to benefit from uncertainty without being fully exposed to downside. It is associated with flexibility, liquidity, rights, convexity and the ability to change position. But in systemic conditions, optionality becomes broader. It is not only the investor’s ability to move. It is the system’s ability to keep multiple futures open.
A business-as-usual portfolio preserves private optionality through exit and hedging. A sustainability portfolio preserves transition optionality by investing ahead of regulation and market change. A 3°C portfolio preserves spatial optionality by identifying places that may remain viable. A total value-at-risk portfolio preserves civilisational optionality by rebuilding the conditions that keep future pathways open.
The crucial distinction is between private optionality and shared optionality.
Private optionality allows an investor to escape a deteriorating context. Shared optionality improves the context so that more actors retain the capacity to adapt. In a systemic-risk world, private optionality may become self-defeating if it accelerates the collapse of shared optionality. If everyone seeks exit, exit becomes impossible. If everyone seeks safe havens, safe havens become contested. If everyone hedges risk rather than reducing it, the underlying risk compounds.
The more systemic the risk, the more valuable shared optionality becomes.
This is the deeper logic of total value-at-risk investing. It is not simply trying to generate returns from foundational goods. It is trying to preserve the option space within which any future return remains possible.
From asset returns to reserve maintenance
The central shift is from asset-based investing to reserve-based investing.
Traditional finance asks what the expected return of an asset is. A more systemic finance asks what reserves that asset depends on. A deeper finance asks what investment is required to preserve or regenerate those reserves.
This changes how value creation is understood.
Cooling a city is not merely an adaptation cost. It preserves labour productivity, public health, real estate value, energy system stability, social cohesion and institutional legitimacy. Restoring a watershed is not merely environmental spending. It preserves agriculture, water security, flood resilience, insurance viability, biodiversity, settlement stability and public balance sheets. Investing in care is not merely social expenditure. It preserves human capability, labour participation, intergenerational continuity, public trust and the legitimacy of the social contract.
The same is true of civic intelligence. Building the capacity of societies to perceive risk, coordinate response, correct failure and avoid catastrophic misallocation is not a democratic luxury. It is part of the operating infrastructure of future value. Strengthening local food systems is not merely a lifestyle or sustainability choice. It preserves nutritional security, supply-chain redundancy, regional economies, land stewardship and social stability. Investing in institutional capacity is not overhead. It is the infrastructure through which societies convert risk into coordinated response.
These are not peripheral benefits. They are systemic operating gains.
The financial system has been trained to see value where it can be privately captured. But the next era of value will increasingly depend on what can be systemically preserved.
From return to total operating gain
This requires a new investment language.
Return may remains necessary, but it is insufficient. In a world of systemic risk, we also need to understand total operating gain.
Total operating gain refers to the wider improvement in the conditions that allow systems to function. It includes avoided losses, reduced volatility, preserved insurability, lower public liabilities, stronger institutions, enhanced ecological function, improved social trust, greater coordination capacity, reduced conflict and expanded future optionality.
This is not soft value. It is not a moral add-on. It is increasingly the basis of hard economic continuity.
If a city remains insurable because flood risk is reduced, that is operating gain. If a region preserves water security through watershed restoration, that is operating gain. If a society maintains trust through better civic feedback and institutional correction, that is operating gain. If a food system becomes less vulnerable to climatic and geopolitical shocks, that is operating gain. If a public balance sheet avoids future liabilities through prevention, that is operating gain. If transition costs are reduced for households, preserving political legitimacy and adoption capacity, that is operating gain. If a supply chain becomes less exposed to geopolitical fragmentation, that is operating gain. If a region reduces contagion risk across neighbouring places, that is operating gain. If risk is made visible early enough to act before collapse, that is operating gain.
The challenge is that operating gains are often distributed, delayed, counterfactual and multi-beneficiary. They do not sit neatly on one balance sheet. This is why they are underinvested in.
The next generation of finance must therefore develop mechanisms to recognise, attribute, pool and govern these gains. This may require new forms of contractual infrastructure, outcome vehicles, contribution-to-claim protocols, pooled risk structures, public-private compacts, civic balance sheets, long-duration capital arrangements and new forms of mission equity.
The strategic opportunity is not simply to find new assets. It is to build the economic architecture through which systemic value can become operable.
From thesis to investment architecture
If this argument is right, then the next frontier is not merely analytical. It is institutional and contractual. The financial system will need vehicles capable of investing in reserve conditions that sit across multiple balance sheets, multiple beneficiaries and multiple time horizons.
In practice, this points towards new forms of investment architecture: resilience funds, adaptation vehicles, transition affordability funds, watershed and food-system compacts, place-based infrastructure portfolios, insurance-linked prevention finance, civic balance sheets, outcome vehicles and contribution-to-claim protocols that allow distributed operating gains to be recognised and governed.
The challenge is not simply capital supply. There is substantial capital looking for credible future-facing mandates. The harder challenge is mandate construction. How does avoided loss become investable? How does reduced volatility become attributable? How does preserved insurability become part of a return logic? How does ecological repair create legitimate claims without becoming extractive financialisation? How do multiple beneficiaries co-pay for systemic value? How do places govern the value created by resilience without surrendering control over foundational goods?
This is where finance meets institutional design. The next generation of investment will not only require new asset classes. It will require new agreements, new public-private compacts, new accounting systems, new legitimacy structures and new forms of long-duration stewardship.
The failure of exit
One of the deepest assumptions of modern finance is the possibility of exit.
If a position becomes too exposed, capital can move. If a geography becomes too risky, capital can rotate. If a sector becomes stranded, capital can reallocate. If a jurisdiction becomes unstable, capital can seek another one.
Exit is the silent reserve of business-as-usual investing.
But systemic risk weakens the exit assumption. When risks become correlated, everyone seeks exit at once. When insurance withdraws, liquidity falls. When climate risk becomes visible, buyers demand discounts. When political systems become unstable, capital controls, regulation or public backlash may limit mobility. When the same risks affect multiple geographies, diversification loses power. When foundational systems degrade, there may be no clean outside.
This does not mean exit disappears. Liquidity will remain central to finance. But in systemic risk conditions, exit cannot remain the primary theory of safety. When risks become correlated and context-wide, safety increasingly depends on maintaining the field rather than leaving the position.
At that point, the promise of exit gives way to the necessity of repair.
This is a profound shift. Finance has long organised itself around the option to leave. But the coming era will increasingly reward those who can help places, systems and institutions remain viable.
The frontier is not only liquid capital. It is committed capital with the intelligence, legitimacy and governance capacity to rebuild the conditions of value.
The failure mode of each strategy
Each strategy contains its own failure mode.
The business-as-usual failure mode is the belief that instability can always be hedged, insured or exited. This works until risk becomes systemic, correlated and politically non-exitable.
The sustainability failure mode is the belief that transition will become normal because it is rational. This works only if consumers can pay, governments can invest, supply chains can deliver, ecological systems retain repairable headroom and the social contract can absorb the costs of transition.
The 3°C failure mode is the belief that stability can be privately secured in favoured locations. This works only if breakdown remains bounded, contagion can be managed and financial economics is not subordinated by security economics.
The total value-at-risk failure mode is the belief that recognising systemic risk is enough. It is not. Risk must become visible early enough, actionable quickly enough, legitimate enough and operationalised before optionality closes.
There is also a failure mode at the level of the meta-strategy: the belief that assumptions can be updated without changing institutions. They cannot. A portfolio may intellectually recognise that its assumptions are decaying, but if its mandate, governance, incentives and vehicles remain fixed, it will still be trapped in the previous strategy.
These failure modes matter because they reveal the deeper transition in investment logic. The old investment paradigm asks how to preserve portfolio value against external shocks. The emerging paradigm asks how to preserve the conditions that make portfolio value possible.
The real portfolio question
The four strategies should not be treated as mutually exclusive. Most serious capital allocators will hold some version of all four.
There will still be business-as-usual arbitrage. There will still be sustainability alpha. There will be growing interest in resilient locations and adaptive infrastructure. There will be an emerging class of systemic investments designed to preserve foundational optionality. And there will be an increasingly important capability above them all: the governance of the assumptions that determine which strategy remains valid under changing conditions.
The strategic question is one of weighting, timing and worldview.
How much capital remains trapped in the assumption that instability is hedgeable? How much capital is positioned for an orderly and affordable sustainability transition? How much capital is betting that stability can be spatially bounded in a high-disruption climate world? How much capital is capable of investing in the foundational goods required to prevent total value destruction? How much capital has the institutional capacity to change its assumptions dynamically? And, most importantly, how much capital is actually renewing the reserve conditions on which its own future returns depend?
This is the real portfolio question of the coming decade.
Not simply: what should we invest in?
But: what theory of the future are we underwriting, what assumptions does that theory depend on, and what reserves must be rebuilt for those assumptions to remain viable?
Closing provocation
Finance has always claimed to be forward-looking. But much of it is only forward-looking within the assumptions of yesterday’s world.
It assumes insurance will remain available. It assumes liquidity will be there when needed. It assumes exit will remain possible. It assumes consumers will have purchasing power. It assumes governments will have fiscal capacity. It assumes public systems will absorb shocks. It assumes global supply chains will remain coherent. It assumes ecological systems will continue to function. It assumes political legitimacy will hold. It assumes infrastructure will remain reliable. It assumes stable locations can remain insulated. It assumes markets will continue to price value even as security economics expands. It assumes risk will become visible early enough to act. It assumes that when assumptions change, institutions will be able to change with them.
These are no longer safe assumptions.
The age of systemic risk reveals that finance has been living off reserves it did not account for. The next era of finance will be defined by whether it can move from exploiting those reserves to rebuilding them.
This is not a marginal adjustment to ESG. It is not simply another sustainability thesis. It is a deeper shift in the object of investment itself.
The central investment problem of the coming decade may therefore be less about finding the next asset class than about preserving the conditions under which asset classes remain meaningful. The frontier is no longer only investing in assets. It is investing in the reserve conditions that make assets valuable.
But even that is not quite the final formulation. The deepest frontier is the capacity to manage the assumptions beneath the assets: to know which future one is underwriting, to see when that future is becoming less plausible, and to move capital not merely away from failing assumptions, but towards rebuilding the reserves that make better assumptions possible.
It is, in the most literal sense, investing in the possibility of a future.
Let's (re)build the conditions that make long-term belonging, resilience, and shared prosperity possible.
This analysis is brilliant. The argument that capital needs to stop exiting as risk mitigation echoes the moment nomadic tribes coalesced into nations with a shared affinity their land, not because the land was safe, but because investment in place became a more viable strategy for planning and anticipation. The reserve conditions you describe are essentially what a civilization bets on when it decides to extend the time horizon of its goals.
The only part I don't understand is why there no arrow from the meta strategy (the portfolio of assumptions) to Option D?